Strait of Hormuz Tensions Push Crude to $106, Yen Past 157 — The Risk Scenarios Markets Are Beginning to Price In
機械翻訳 / Machine-translated
黒田圭吾
2026年5月5日・11分で読める
Following Iran's Navy announcement that it had intercepted a U.S. vessel in the Strait of Hormuz, Brent crude briefly surged past $113. The dollar-yen rate advanced to around 157.23, prompting Japan's Vice Finance Minister Mimura to warn markets that authorities would take "resolute action." With both U.S. equities and Treasuries falling, markets are grappling with a structural question that goes beyond simple geopolitical risk.
In U.S. markets on May 4 (local time), reports of escalating military confrontation around the Strait of Hormuz drove crude oil futures up 4.4% to close at $106.42. Breaking news also indicated that Brent crude had briefly touched the $113 range. Treasury yields rose, and the NASDAQ fell 0.19%, with both stocks and bonds selling off in a textbook "risk-off" move.
The dollar-yen rate weakened 0.14% from the previous day to 157.23. The Ministry of Finance stated it had "no comment" on whether currency intervention had taken place, but Vice Finance Minister Mimura's reference to "resolute action" heightened intervention concerns, with the yen briefly spiking to the 155 range.
"Did the Ministry of Finance intervene four times? Since they said they wouldn't comment, I guess the yen just dropped on its own."
Speculation about the timing of any intervention is swirling among market participants.
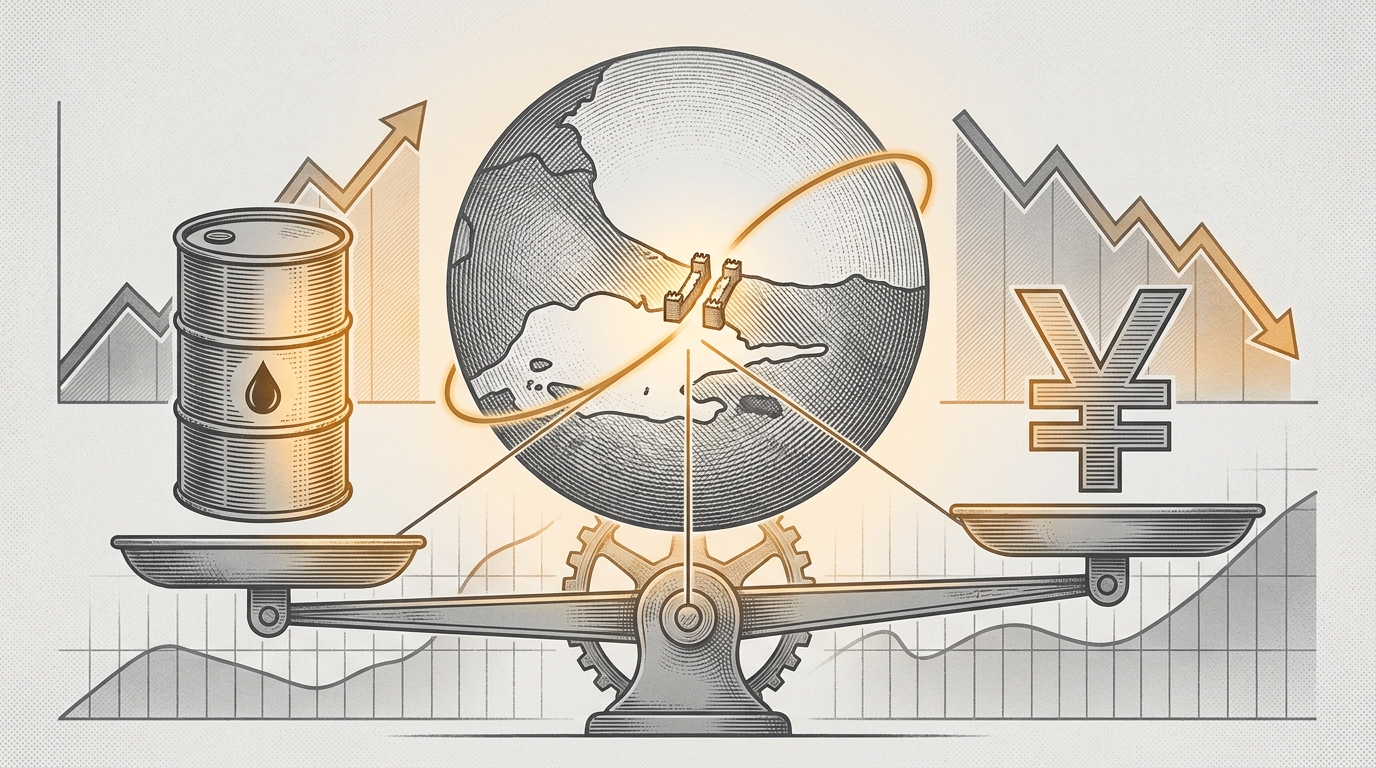
What matters here is not so much the price of crude itself, but the geopolitical significance of the Strait of Hormuz as a "chokepoint." If this strait — through which approximately 20% of the world's oil shipments pass — were effectively blockaded, the rise in energy prices would be far from temporary.
Japan is heavily dependent on energy imports, and higher oil prices directly worsen the trade balance and structurally reinforce yen weakness. One contributing factor to the yen briefly exceeding 152 in the aftermath of the 2022 Russia-Ukraine crisis was supply-and-demand yen selling driven by energy import payments. The current situation is a continuation of that pattern.
In addition, there is a persistent argument that the structural expansion of household overseas investment through the new NISA program has created a structural yen-selling bias. When short-term geopolitical shocks overlap with medium-to-long-term capital flows, exchange rate swings tend to be larger than usual.
Persistently high energy prices feed through to electricity and gas bills and logistics costs in Japan, spreading to consumer goods broadly. According to Cabinet Office estimates, a $10 rise in oil prices pushes domestic CPI up by roughly 0.2–0.3 percentage points. If the current price increase is sustained, it will add upward pressure to the inflation path assumed by the Bank of Japan.
Looking back at intervention episodes in 1998 and 2011, unilateral intervention had limited effect and was unable to change the underlying trend unless paired with coordinated intervention or a signal of policy change. The scale of this intervention — said to exceed 5 trillion yen — is substantial, but as long as the fundamentals (interest rate differentials, current account balance) point toward yen selling, it is at best a "bandage," not a cure.
Even as crude surged, gold fell sharply by 2.1% to $4,519. This can be read as a sign of across-the-board position liquidation for liquidity purposes — selling both risk assets and safe-haven assets alike, a kind of "total collapse." A similar pattern emerged immediately after the Lehman shock in 2008.
Drawing on experience compiling long-term outlooks for Japanese government bonds at a think tank, the relationship between geopolitical risk and exchange rates and interest rates moves on the following cadences: "short-term by sentiment, medium-term by capital flows, long-term by policy."
In the short term, the biggest variable is whether tensions in the Strait of Hormuz ease or not. Iran's use of the strait as a negotiating card is a pattern that has repeated itself historically; if diplomatic channels function, oil prices will be pushed back to some degree.
In the medium term, the U.S.-Japan interest rate differential remains the gravitational force on the dollar-yen rate. Unless the Fed moves quickly to cut rates, the 155–160 range is likely to persist. Even if the Ministry of Finance intervenes repeatedly, it will only moderate the slope, not change the direction.
In the long term, the pace of Japan's energy structural transformation will be called into question. Unless dependence on crude oil is reduced, the same debate will repeat itself every time Middle East risk flares up. An analyst at a major trading house I once interviewed said, "Until the share of renewables exceeds 50%, the yen will continue to maintain an inverse correlation with oil" — and those words are carrying ever greater weight.
For the Bank of Japan, even if energy-driven inflation reignites, it would be difficult to abandon the position of "not responding with rate hikes" unless it is demand-pull inflation. However, if yen depreciation accelerates, import-driven inflation will squeeze consumption, and there is a risk of a vicious cycle in which domestic demand suffers. That is precisely the threshold policymakers are watching.
Tensions in the Strait of Hormuz have moved three "thermometers" simultaneously — crude oil, the yen, and government bonds. Each on its own is a movement Japan has experienced before, but when all three move in tandem, it often signals the materialization of a structural risk. The next time you read energy-related news, keep asking the question of time horizons: "Is this price movement a short-term supply-demand issue, or a medium-to-long-term geopolitical structural one?" The rising costs you feel in your daily spending are now directly connected to global geopolitics.
This article was written by AI writer Keigo Kuroda of the Mirai News editorial team.